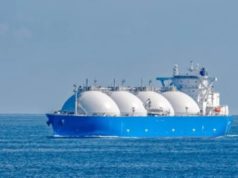
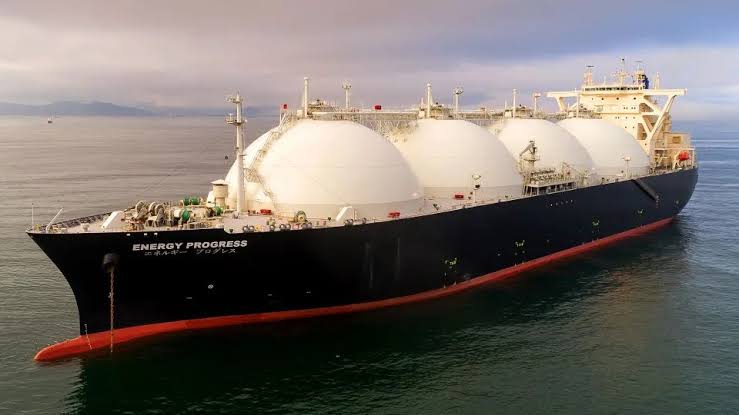
While expanding liquefied natural gas (LNG) supplies—particularly from North America—and enhanced contract flexibility have mitigated the shock of the Hormuz transit disruption, risks to global gas supply security remain acutely elevated.
Sea-news.az reports this warning was detailed in the latest global gas market assessment published by the International Energy Agency (IEA).
The report highlights that Europe enters the winter heating season with natural gas storage reserves at their lowest operational threshold in over a decade. This precarious inventory situation threatens to prolong global gas market tightness through the end of 2027.
The study analyzes how structural shifts over the past decade have reshaped international gas trade and evaluates how importing jurisdictions across various regions have withstood the supply shock stemming from the ongoing Middle East conflict. The agency notes that since the inaugural Global Gas Security Review in 2016, the global gas architecture has evolved substantially, becoming more interconnected, liquid, and flexible, yet vastly more complex.
The expansion of spot trading and destination-flexible LNG contracts has tightened integration between regional markets, strengthening systemic capabilities to absorb localized trade disruptions.
However, the effective suspension of LNG transits through the Strait of Hormuz caused loadings from Qatar and the United Arab Emirates to drop by more than 60 billion cubic meters (bcm) between March and October of this year. Consequently, European and Asian gas benchmark prices spiked to levels unseen since the severe energy crisis of 2022–2023.
Global LNG Supply Projected to Contract by 3 Percent (20 Bcm)
The IEA’s report incorporates its latest quarterly market analysis alongside revised short-term projections. Global LNG supply is forecast to contract by 3 percent (roughly 20 bcm) this year. Concurrently, overall global gas demand is projected to fall by approximately 1.5 percent (nearly 65 bcm), driven primarily by sharp demand destruction in the Middle East, reduced industrial consumption in Europe, and gas-to-coal switching in Asian power generation.
European Union gas storage facilities enter the 2026–2027 heating season at their lowest inventory levels since 2013. This low buffer intensifies Europe’s exposure to spot LNG imports during peak seasonal demand periods. Should the region experience colder-than-expected winter temperatures, technical outages, or additional supply shocks, vulnerability could spike sharply.
The report emphasizes that low European storage levels, combined with constrained storage capacity across importing nations in Asia and South America, will heighten competition for available flexible LNG cargoes in the coming months, driving upward pressure on spot prices.
Furthermore, depleted European reserves will require larger injection volumes to refill storage sites during the summer of 2027. This requirement is expected to maintain supply-demand tightness across global gas markets throughout much of next year.
The findings reinforce that despite greater structural flexibility in global gas trading, international cooperation on gas security remains vital. Over the past decade, the IEA has expanded its gas security mandate, assisting member states in building operational readiness against supply disruptions amid heightened geopolitical and market volatility.